


MORTGAGE LENDING
We Are Here To Help
THE TEAM
Your Mortgage Concierge

Helping to make your home buying experience as smooth as possible
MORTGAGE CONCIERGE
Experience The Dedicated Focus
 Another Level of Service
THE TEAM'S WHY
Understand the Heart of Our Team
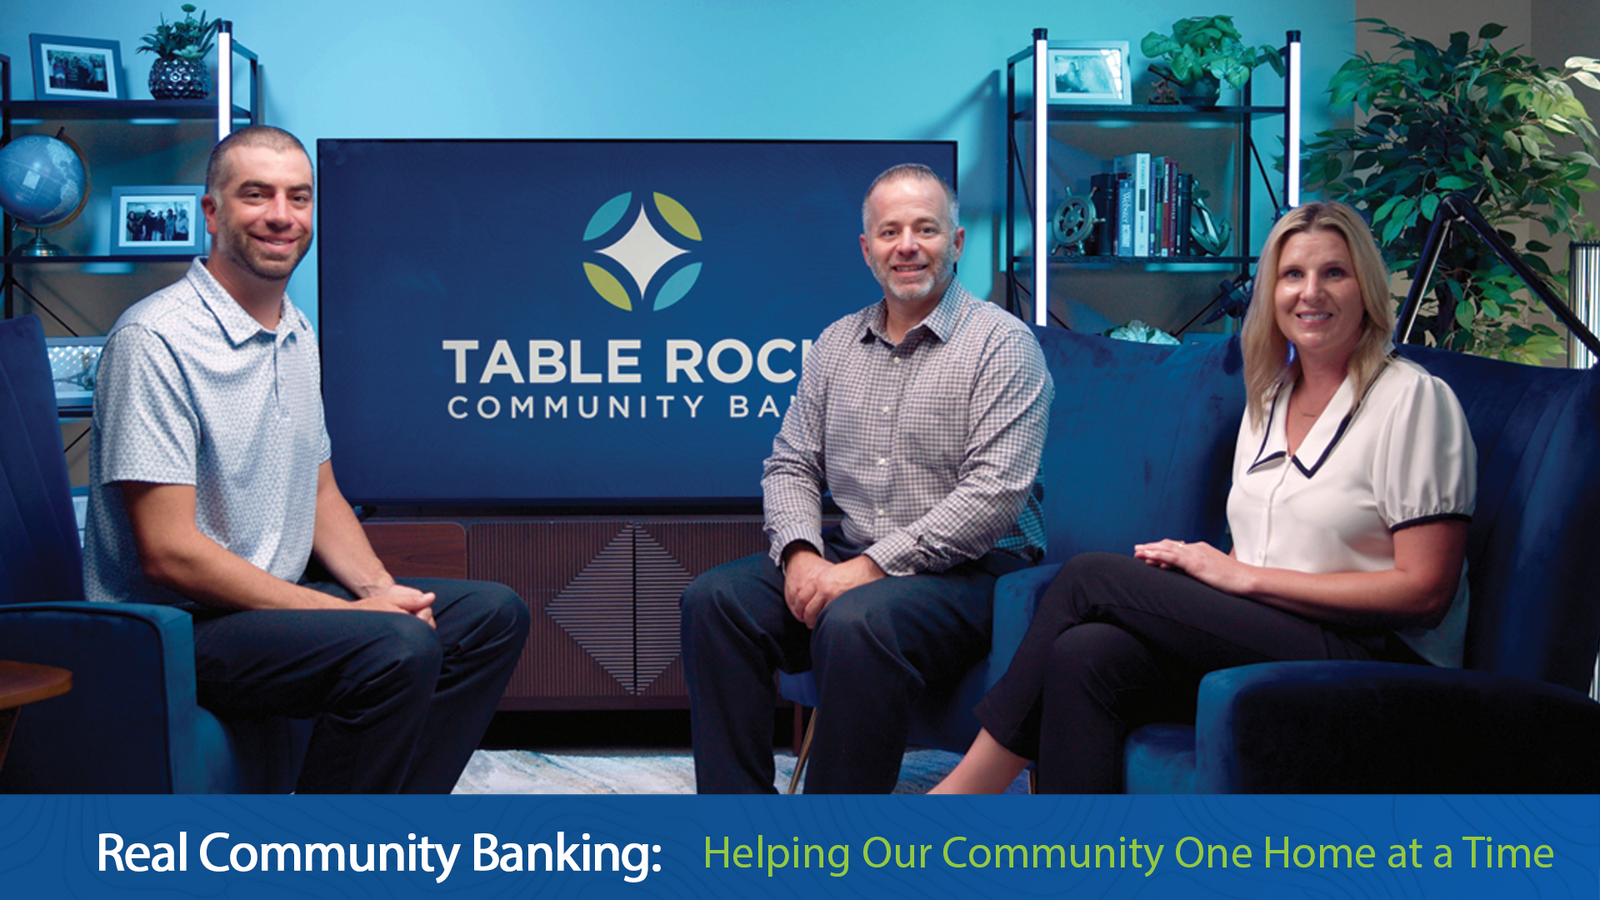
Buying a home is a big moment, and you deserve a team that treats it that way. In this short interview, meet the Table Rock Community Bank mortgage team and hear how we keep the process personal. One dedicated lender, clear communication, and real care from start to closing, so buyers feel supported, not processed.
LOAN TYPES
Talk To Us About the Right Loan For You
A traditional mortgage with competitive rates and flexible terms. Often best for buyers with solid credit and steady income. You will typically need proof of income, assets for down payment and closing costs, acceptable debt-to-income, and an appraisal. Mortgage insurance may apply with lower down payments, but can be avoided with stronger equity.
Starts with a lower fixed rate for a set period, then adjusts based on market conditions. Can fit buyers who plan to move, refinance, or pay down faster. You will need the same basics as most mortgages, plus you should be comfortable qualifying under potential future payment increases, based on lender guidelines.
A government-insured loan designed to make homeownership more accessible with lower down payments and flexible credit guidelines. You will need verified income, acceptable debt-to-income, an appraisal that meets FHA standards, and funds for closing. FHA mortgage insurance is required. Great for first-time buyers or buyers rebuilding credit.
A benefit for eligible veterans, active-duty service members, and some surviving spouses. Often offers no down payment and no monthly mortgage insurance. You will need a Certificate of Eligibility, income and asset verification, a credit review, and a VA appraisal. Closing costs vary, and a VA funding fee may apply depending on eligibility.
A program for eligible rural and some suburban buyers that may offer low or no down payment. You will need to meet income limits, buy in an eligible area, and provide standard documentation like income, assets, and credit history. USDA appraisals and property standards apply, and there are guarantee fees similar to mortgage insurance.
Financing for homes above conforming loan limits. Typically requires stronger credit, higher reserves, and a larger down payment than standard loans. You will usually need detailed income documentation, proof of assets, a strong credit profile, and a thorough appraisal. Underwriting can be more documentation-heavy to support larger loan amounts.
Programs designed to help first-time buyers with down payment assistance, reduced costs, or flexible guidelines depending on the program. Requirements vary, but often include homebuyer education, income limits, and occupancy rules. You will still need standard documents like pay stubs, tax returns, bank statements, and an appraisal.
HAVE QUESTIONS
Need Answers Before You Apply